OPTION 1 · YOU SUBMIT
Inspection & documentation only
We inspect, photograph and prepare a detailed repair estimate.
You submit the documentation to your insurance carrier yourself.
Request documentation only →Escambia County Insurance-Approved Contractors
On-site storm-damage inspections, measured repair scopes and Xactimate estimates for property owners with an already-filed claim.
FILED CLAIM + PROOF REQUIRED
Upload your carrier’s claim confirmation so we can review your request before scheduling.
Documentation that tells the whole repair story
A documented estimate supports review of the repair scope—not a guarantee of coverage or payment.
OPTION 1 · YOU SUBMIT
We inspect, photograph and prepare a detailed repair estimate.
You submit the documentation to your insurance carrier yourself.
Request documentation only →OPTION 2 · CONTRACTOR-SIDE SUPPORT
Inspection, Xactimate scope writing, factual repair documentation and coordination of the appropriate trades.
No public adjusting, coverage advice or settlement negotiation.
Request contractor-side support →From our field files
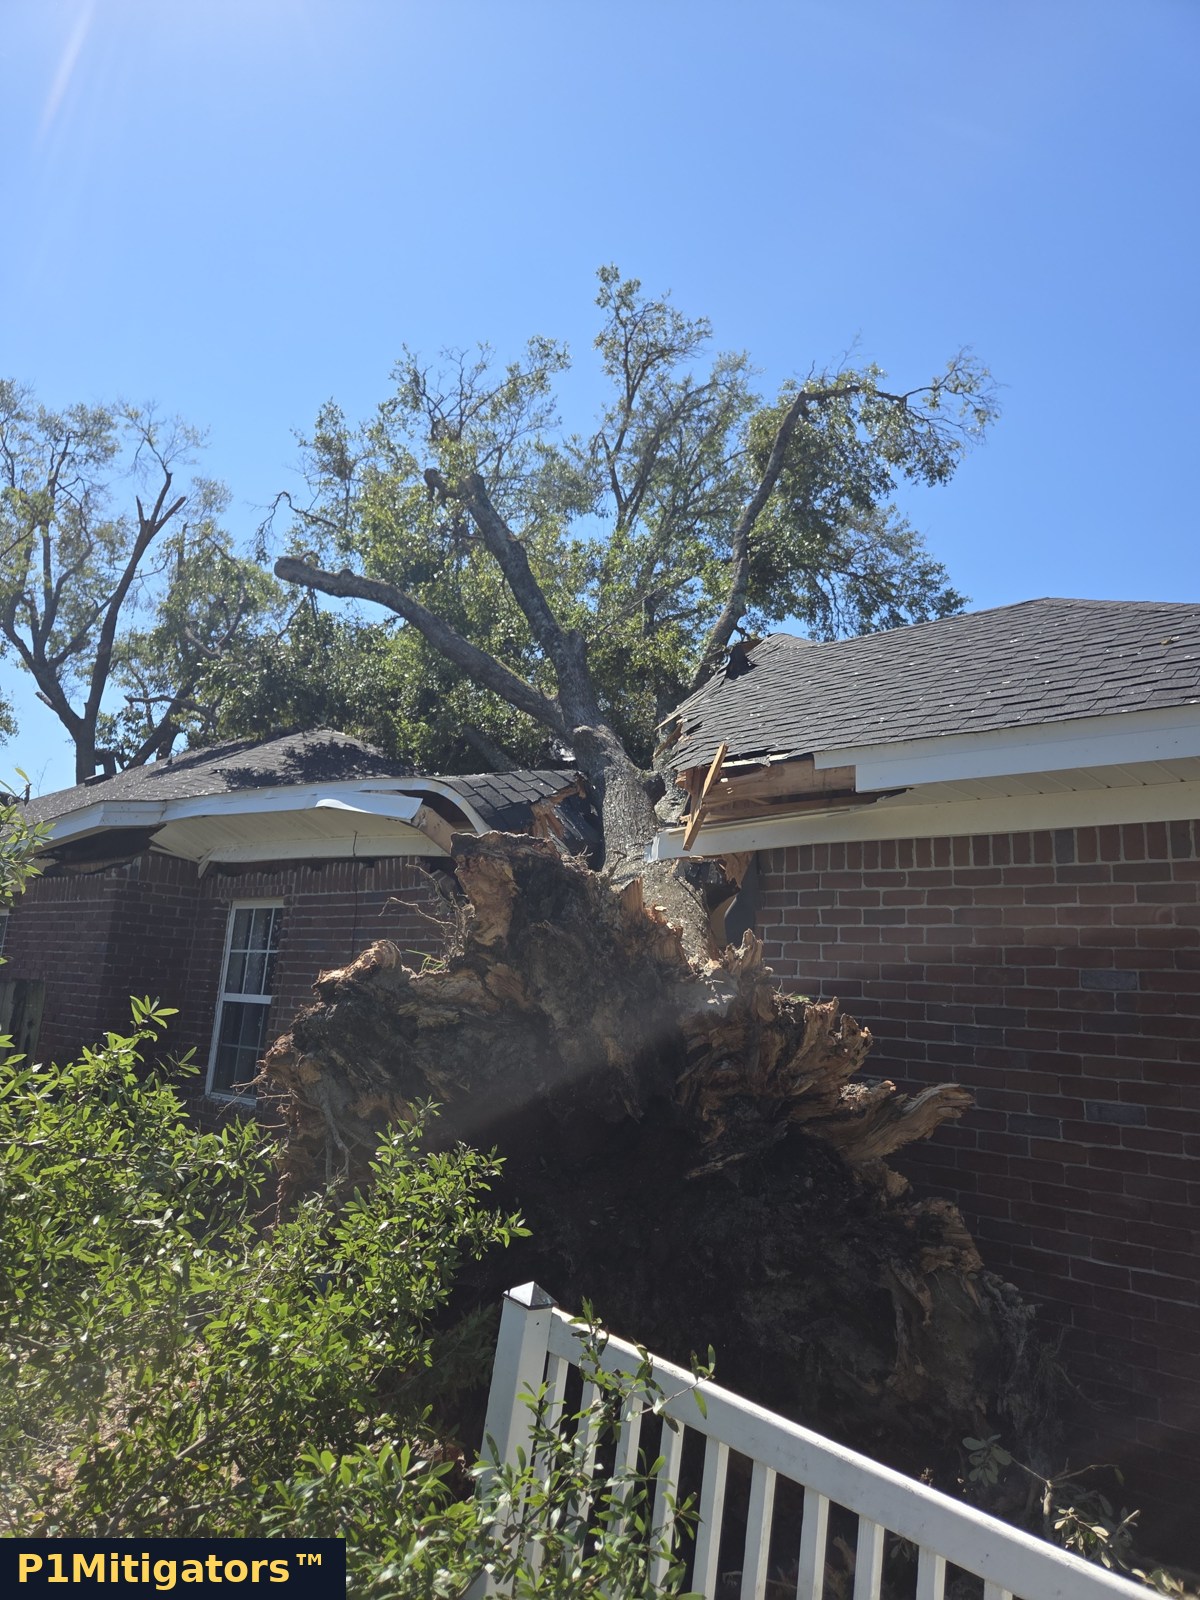
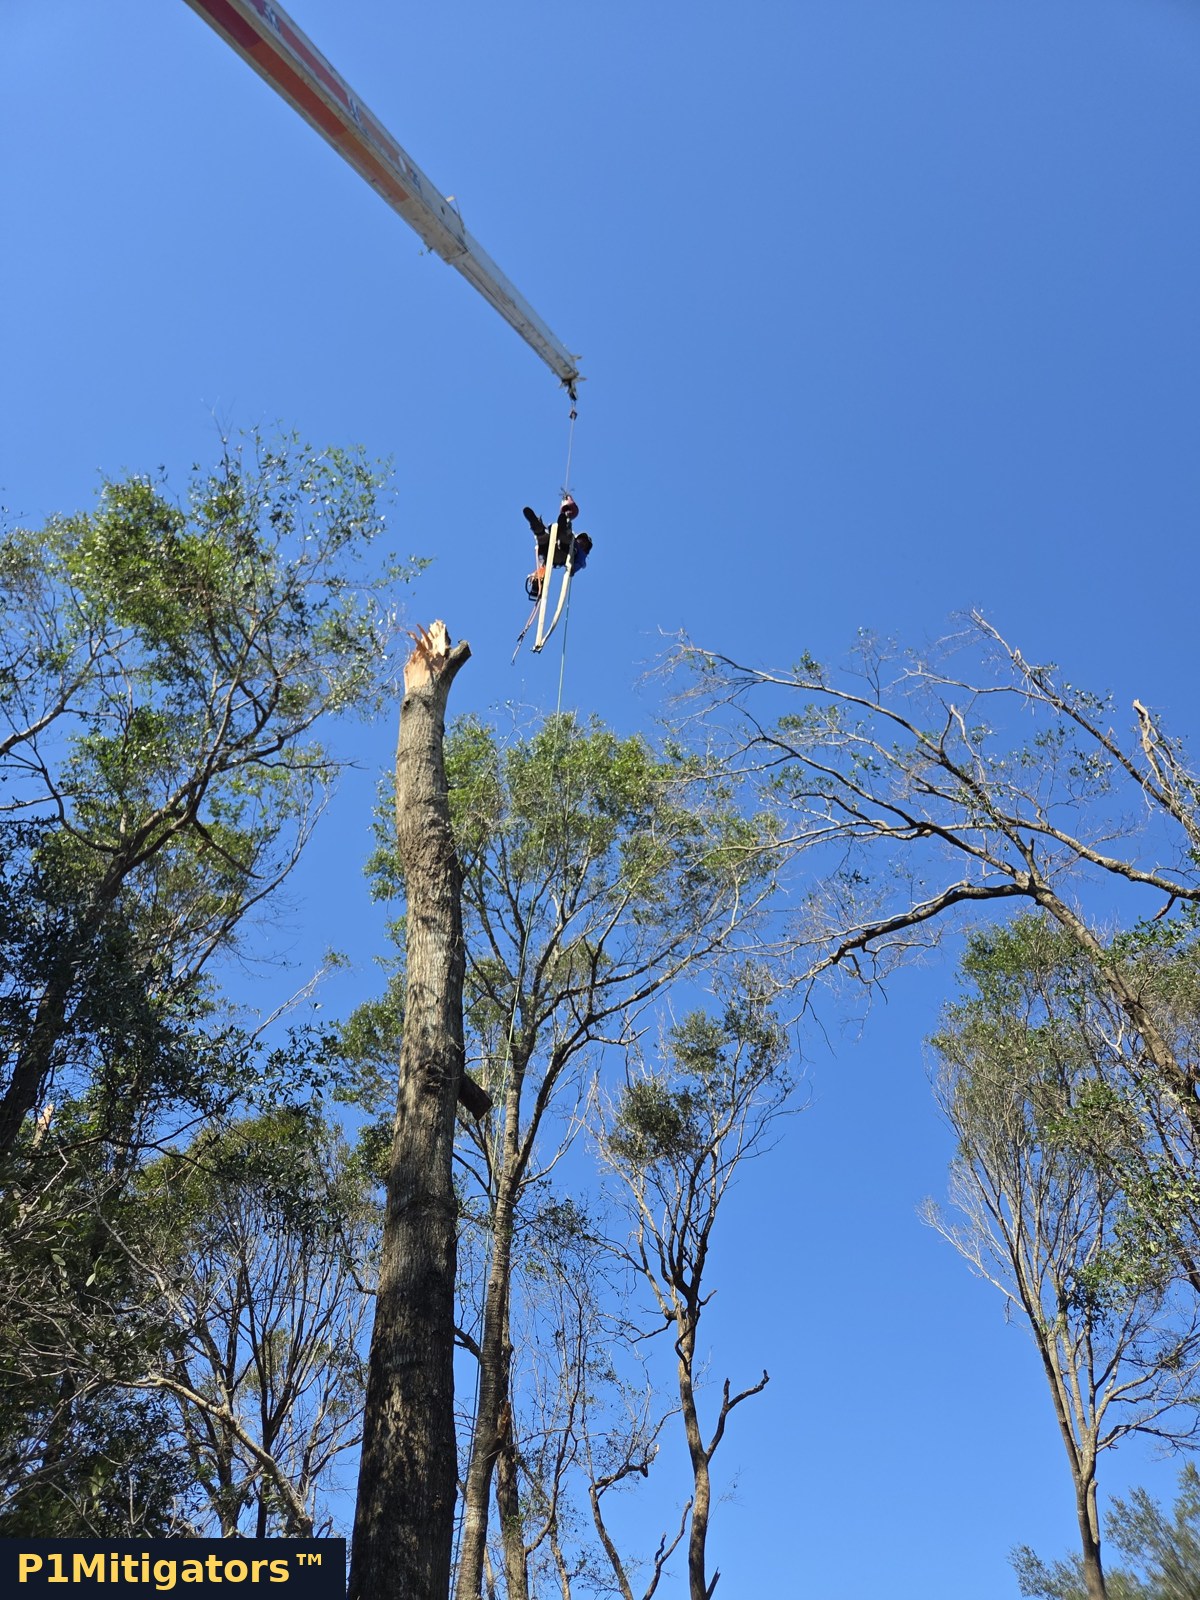
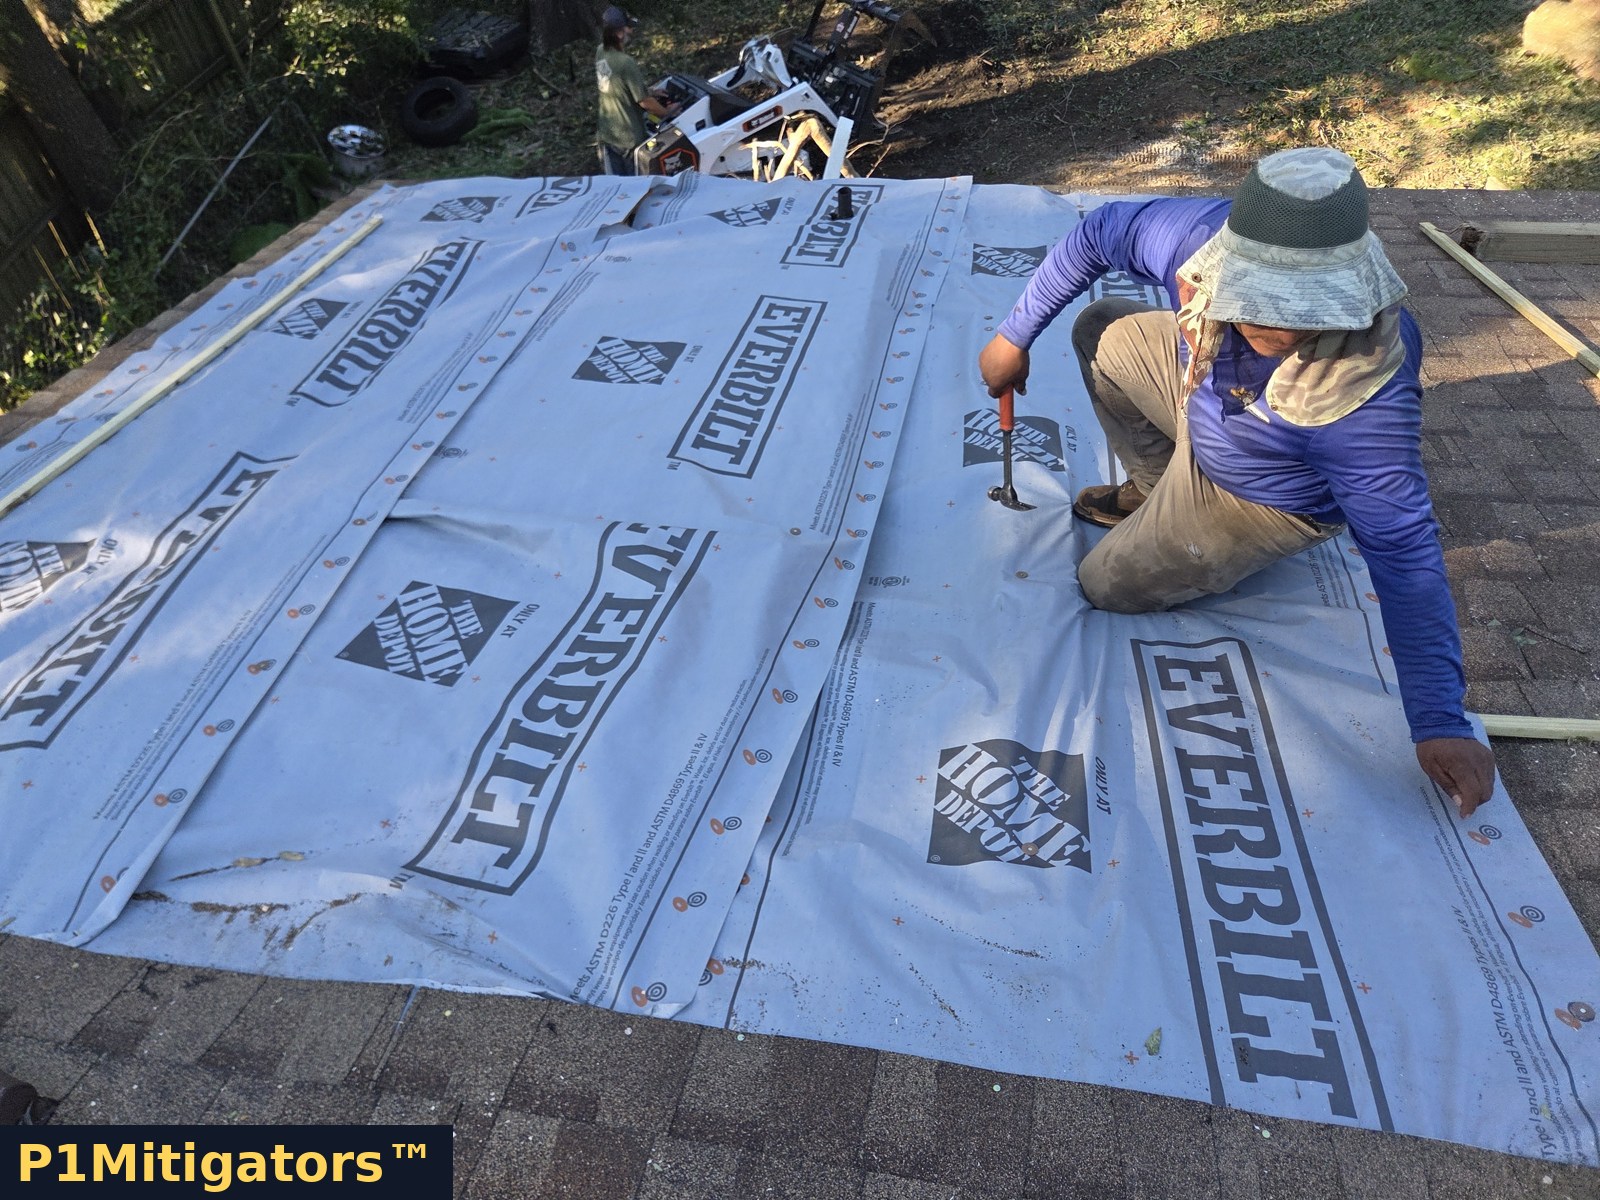
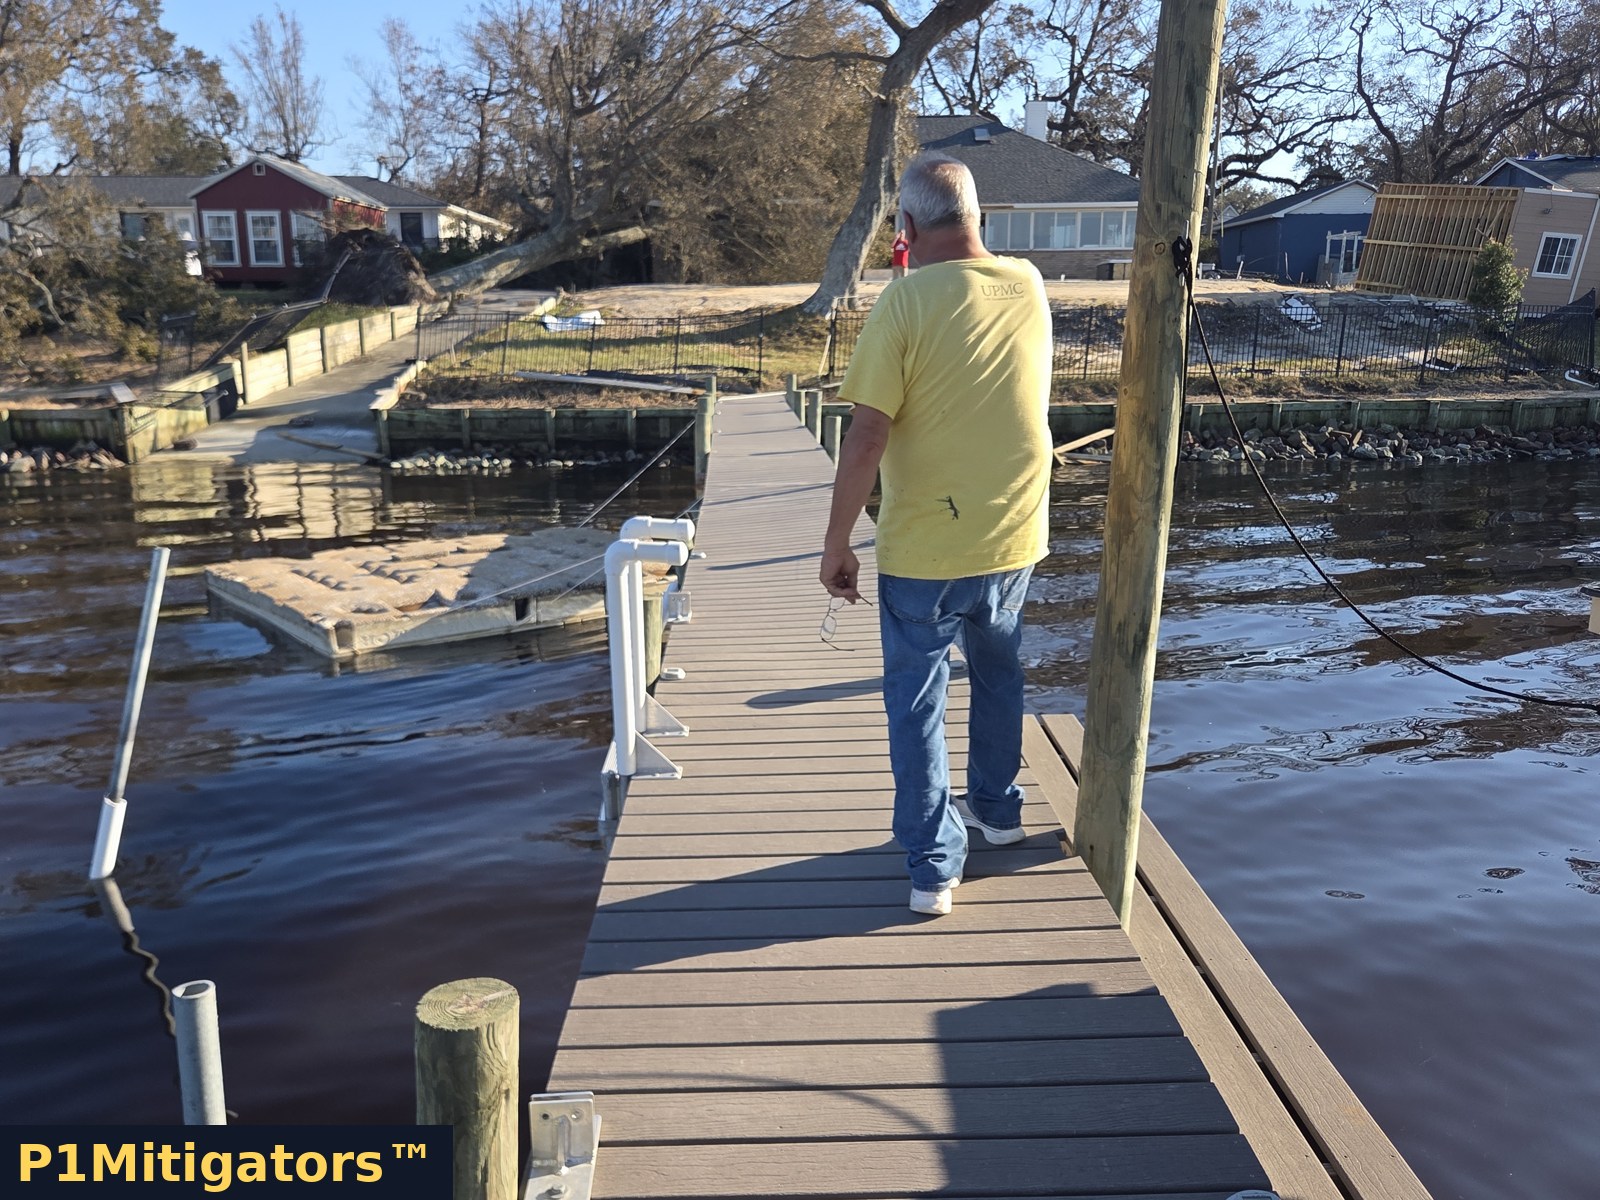
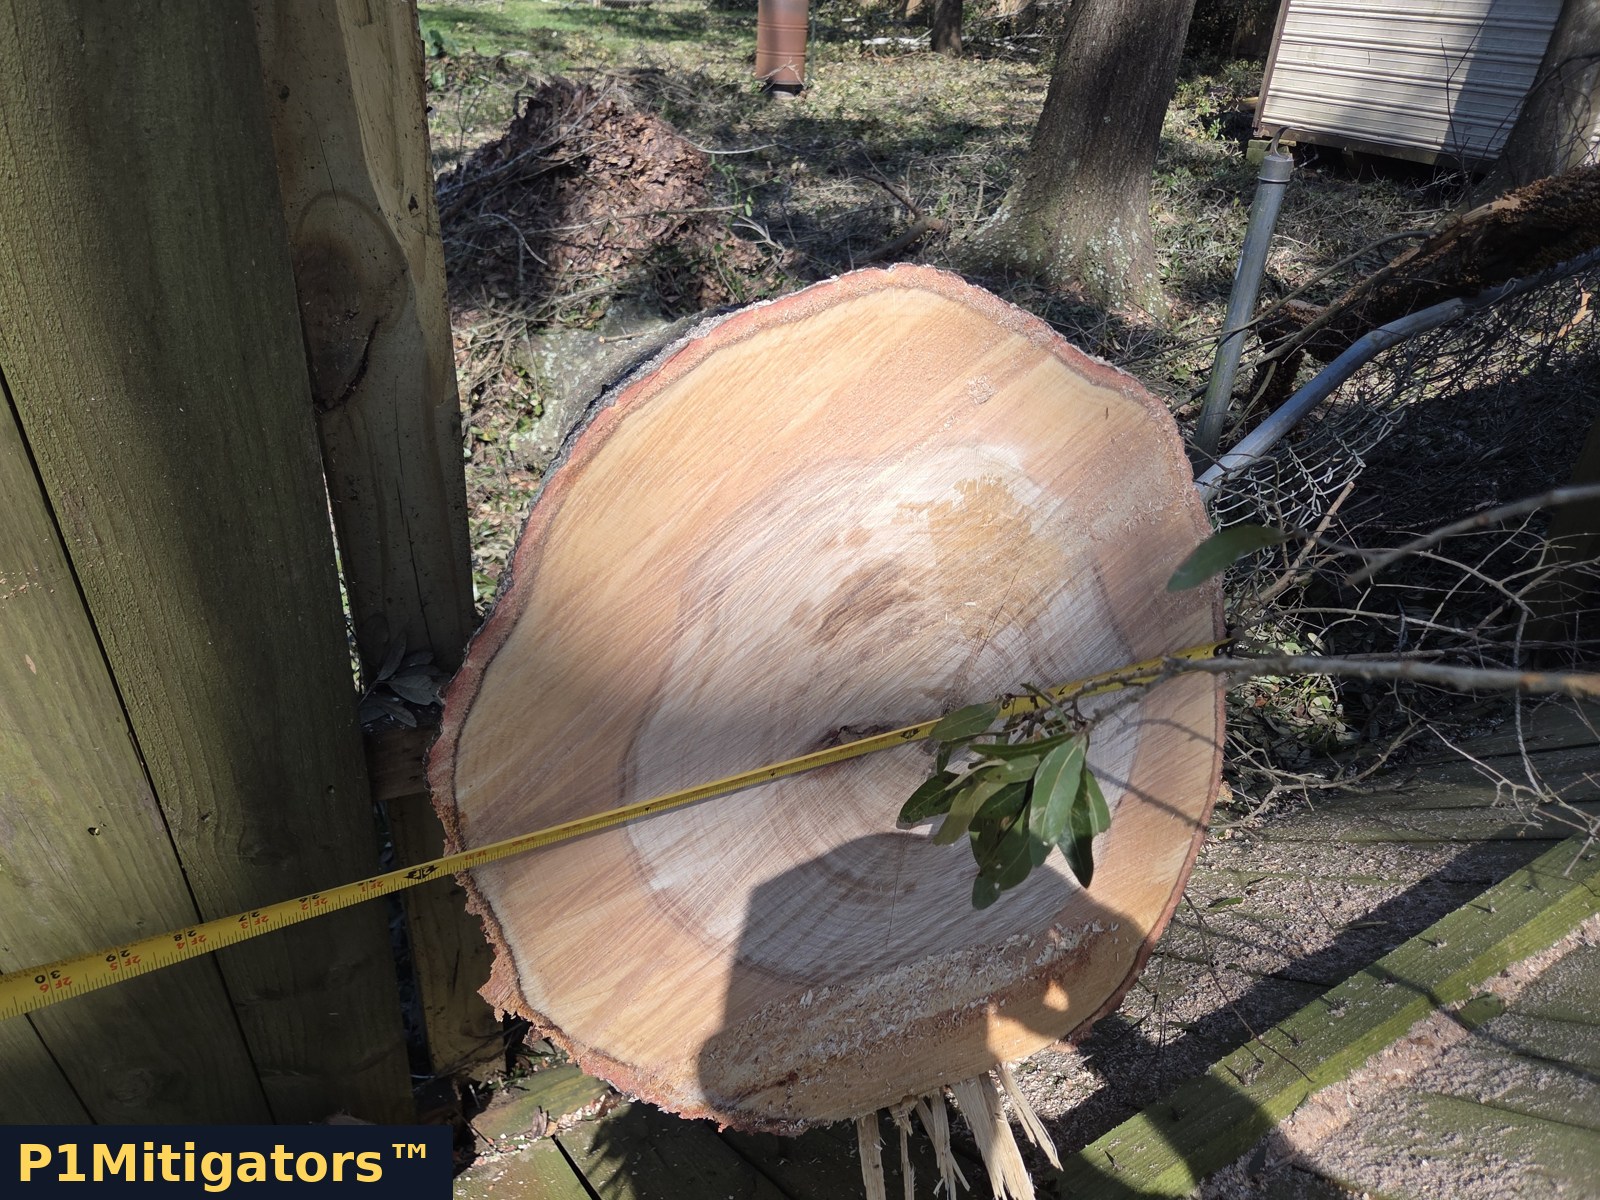
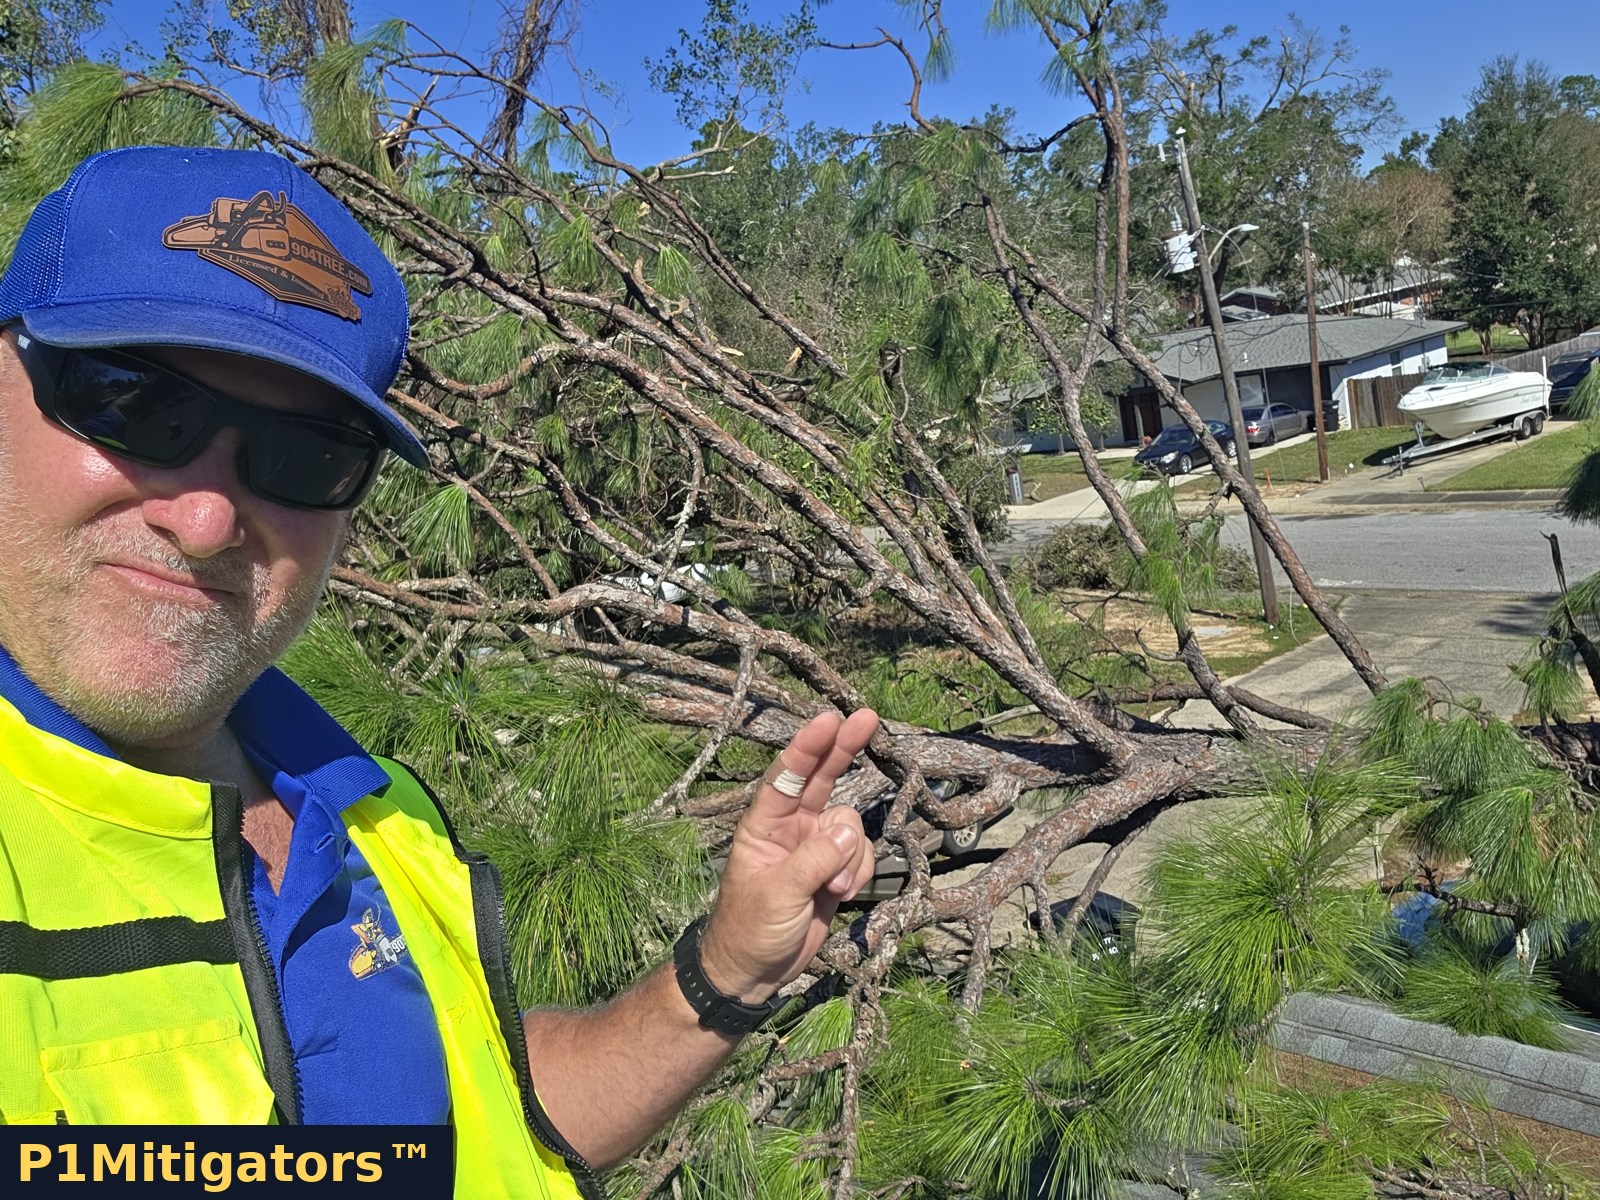
Owner-supplied field photos show the damage, measurements and trade work that a detailed repair record can capture.
Photos illustrate field work; they do not identify every pictured property as a Pensacola location.
Filed storm claims only
Already filed your claim? Tell us who, what and where—and upload proof.
We review your claim documentation before confirming eligibility, service scope, fees and an appointment.
Inspections · Xactimate estimating · Emergency tarping · Consulting · Vetted trade coordination
Independent contractors perform roofing, tree work, fencing and other construction repairs.
A coastal property near Perdido Key, a residential lot in Ferry Pass and a rural parcel near Molino can require very different equipment and access plans.
Explain the property layout, affected structures and any restricted access before choosing a contractor.
Roofing, electrical and other regulated trades require the appropriate credentials for that work; one company’s license does not authorize every company involved.
We check the fit between the job and the assigned trade rather than advertising a single crew that does everything.
The phrase “insurance-approved contractors in Escambia County” does not mean the county or every insurer endorses a contractor.
We use the term to address homeowners seeking insurance-experienced trades, with credentials and a written scope that can be reviewed.
Carrier preferred-vendor status, payment authorization and policy requirements must be confirmed with the insurer for your particular claim.
P1Mitigators™ does not guarantee claim proceeds, waive policy requirements or represent itself as a government-approved disaster contractor.
Request documents for the actual company you will contract with, then check whether they apply to the work and remain current.
Discuss staging, removal routes, site protection and utility conflicts before equipment arrives.
For multiple buildings or long fence runs, identify the limits of work explicitly so separate bids can be compared on the same basis.
Do not treat a verbal statement that “insurance handles it” as a substitute for written payment terms.
We provide inspections, scope writing, estimating and coordination while the selected independent contractors remain responsible for their trade work.
A common job record keeps roofing, tree-related work, fencing, debris and interior tasks visible without merging their contractual responsibilities.
For unincorporated addresses, the contractor should consult Escambia County about applicable permits and inspection requirements.
For sites in Pensacola city limits, use the city’s process instead; contact us with your address so we can start in the right place.
Yes; contact us about Escambia County, Florida properties and we will confirm the scope, safe access and available trade coverage for the address.
No government endorsement is implied; use official agencies for disaster assistance and independently verify the contractor’s credentials.
Review your policy duties and carrier instructions, document reasonable emergency mitigation, and confirm any required approvals for permanent repairs with your insurer.
Tell us where the damage is, what has already been documented and which trades you need coordinated.